与英文对照
与英文对照
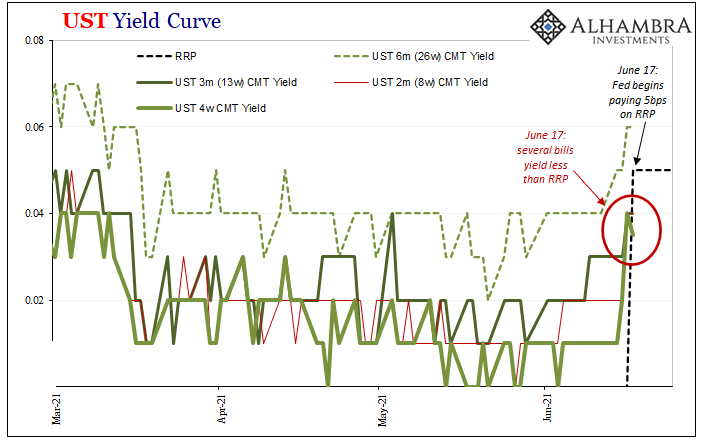
Some background reading: Detailed & Simplified As we all know, usage of the ON RRP Facility just jumped up over $200B, setting a new record at $755.8 billion from now 68 counterparties. Why? Well, during the FOMC meetings, the Fed announced a few things around QE that are circulating through MSM, freaking everyone out about there being 'too much money' and risks of inflation - but a key change that isn't getting as much attention is their decision to raise the IOR and ON RRP rate 5 basis points (.05%), effectively trying to raise the 'floor' of the FFR. (If this doesn't make sense to you, please read this explanation) Long story short, the Fed is now incentivizing more usage of the facility in its efforts to raise the interest rates away from negative territory, by offering to pay counterparties 5 basis points instead of 0 to park cash every night. This seems counterintuitive right, since continued QE is pumping cash into the system, and now the Fed is paying to take it back out at the end of each day - but it actually makes sense when you look at the affect it has (or should have) on short-term interest rates in the open market. While the ON RRP rate was still 0, we could all assume that the 'too much money' narrative was in fact the issue. However, something interesting happened to short-term T-bill yields yesterday when the ON RRP rate was lifted:
与英文对照
short-term yields went the WRONG DIRECTION
与英文对照
What does this mean? Well, the goal was to start easing yields back up from near-zero or potentially negative levels by lifting the 'floor' of the ON RRP. If the issue was purely due to too much money being in the system, it would've worked. Banks, MMFs, GSEs, etc. would take the 5 basis points from the Fed and not bother parking their excess cash elsewhere for less interest. So the reverse repo is now at 5, yet bill yields at the 4-, 8-, and 3-month maturities are all less than this. Why? It can only mean this one thing, there is a stark and very dire need for high-quality collateral, otherwise nothing would ever yield below this secured alternative with the Federal Reserve. Who would buy a 4- or 8-week UST bill returning one and a half maybe two basis points less than lending to the Fed secured by the same instrument? They're giving up guaranteed profit This all points to the true underlying issue that we collectively have been yelling about here - there is a MAJOR collateral liquidity issue in the money markets. I WONDER WHY....
与英文对照
edit:
与英文对照
TL;DR
与英文对照
The Fed just inadvertently showed us that the liquidity issue around ON RRP usage isn't 'too much cash' - it's too little collateral. from u/scamiran: There's plenty of liquidity in the market. Solvency? Not so much. But everyone wants to pretend that if there is sufficient liquidity, there must be solvency. That's how you get zombie banks and stagflation. e2: if anyone wants to further learn about this stuff, I highly recommend looking into Jeff Snider as a great place to start - his research into this is the basis of this whole post https://alhambrapartners.com/author/jsnider/ or Alhambra Investments