İngilizce ile karşılaştır
İngilizce ile karşılaştır
u/leisure_rules has pointed me to the OCC - something that I should have been taking a look at since the beginning of my journey into the workings of the Fed. So I decided to look deeper. OP: https://www.reddit.com/r/Superstonk/comments/ocfcfi/occ_rule_in_effect_7121_net_stable_fundi ng_ratio/ TLDR start - and this is not short, as the document is close to 10k pages, with this section of 102 pages alone; After the recent test, it looks like the Fed shat themselves. A new rule was rushed to be introduced by the self-regulating fucks for the banks and split NFSR into 4 categories of application. Despite the rule having been in plan since 2016 and kind of in play, but has a ton of mentions of ‘08 crash.
İngilizce ile karşılaştır
the Fed looking back at the '08 crash - I'll fucking do it again!
İngilizce ile karşılaştır
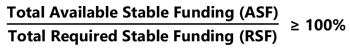
Only the Category II of the banks have submitted a comment that the fucks in Category II will have a fire sale with such strict requirements. Rule passed for more stringent reporting just after the Fed passed the stress test for the banks, allowing them to buy back shares ($12Bn worth, likely the $12Bn that they got from gouging their customers on overdraft fees - no joke ($11Bn in 2019)). Because it is instituted on July 1st, 2021 - allowing the banks to have 10 business days to provide a response/plan on how to deal with their shitty NFSR ratio - we are likely looking at a few weeks if the NFSR ration is rated as bad in some of the banks. But we can expect some movement in the market next week - real movement. Now these agencies are no longer going to count derivatives towards a positive ASF (Available Stable Funding) factor. Further, RSF (Required Stable Funding) factor is set to 100% for the derivatives. This is a double-banana worthy of Rick! Look at the equation (sauce to u/leisure_rules) :
İngilizce ile karşılaştır
NSFR Ratio calculation
İngilizce ile karşılaştır
What is ASF:
İngilizce ile karşılaştır
• Sum of carrying values of the banking organization’s liabilities and regulatory capital,İngilizce ile karşılaştır
each multiplied by a standardized weighting (ASF factor) ranging from 0 to 100%. Here’s the chart of proposed ASF factors: https://www.federalregister.gov/d/2020-26546/p-363 What is RSF:
İngilizce ile karşılaştır
• Sum of the carrying values of its assets, each multiplied by a standardized weightingİngilizce ile karşılaştır
(RSF factor) ranging from 0 to 100% to reflect the relative need for funding over a 1 year horizon based on liquidity characteristics of the asset
İngilizce ile karşılaştır
• PLUS RSF amounts based on the banking organization’s committed facilities andİngilizce ile karşılaştır
derivatives exposure (CRIAND!!!) Here’s the chart of the RSF factors: https://www.federalregister.gov/d/2020-26546/p-481 TLDR end;
İngilizce ile karşılaştır
I’d like to put together a summary of what the fuck is going on - its all in plain English, and I suggest to read it yourself to gain more wrinkles: Introduction The OCC, the Fed, and OCC (agencies) are looking into a 2016 rule to establish NSFR (net stable funding ratio) for any institution with >=$10Bn of consolidated assets. Another two proposals that were being looked into are:
İngilizce ile karşılaştır
• scope of NSFRİngilizce ile karşılaştır
• Complex Institution Liquidity Monitoring Report (FR 2052a) - to basically get self-İngilizce ile karşılaştır
regulating information from the banks (Smells like Goldman’s F3 to anyone?) Background In the ‘08 crash, the banks had issues with risk management, specifically how the banks managed their liabilities to fund their assets. Further, there was an overreliance on short-term, less-stable funding - no shit, they were leveraged to shits. In response, Basel Committee on Banking Supervision (BCBS) created 2 liquidity standards: 1. Liquidity Coverage Ratio (LCR) - for high net cash outflows in a period of stress 2. NFSR - for banks to not be taking handies behind Wendy's after using their credit cards to play the casino Part of the LCR rule was for the banks to hold a specific amount of unencumbered high-quality liquid assets (HQLA) that can be easily converted into cash to meet payments for a 30-day stress period. Along with the “poorly done” Dodd-Frank Act, the board (Fed) decided to adopt an “enhanced prudential standards rule, which established general risk management, liquidity risk management, and stress testing requirements for certain bank holding companies and foreign banking organizations.”
İngilizce ile karşılaştır
PROBLEM: The framework never addressed the relationship between a banking organization’s funding profile and its composition of assets and off-balance commitments. NO SHIT! ANOTHER PROBLEM: The fucking rule was passed AFTER the recent stress test!
İngilizce ile karşılaştır
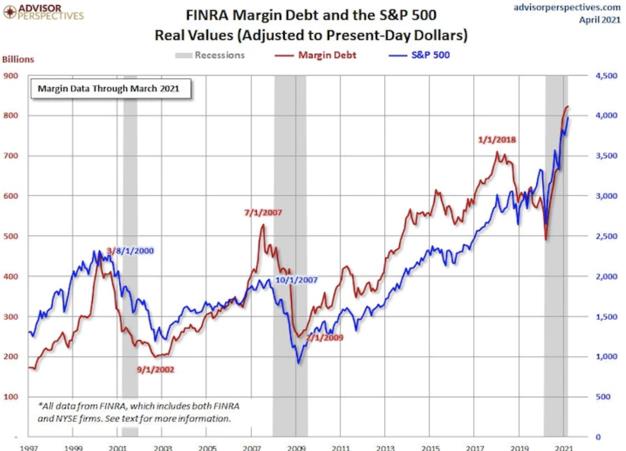
Here’s where the margin debt comes in - being 2x that of ‘00 and ‘08 crashes. Coupled with u/CriandDD - means the OCC is realizing how big of a shitshow it has become, and was never dealt with until Retail started making money and exposing their shit.
İngilizce ile karşılaştır
Margin Debt w/ S&P500
İngilizce ile karşılaştır
Overview of the Proposed Rule and Proposed Scope of Application
İngilizce ile karşılaştır
• The Proposed Stable Funding Requirementİngilizce ile karşılaştır
1. In June ‘16, comments were invited on the rule 2. Rule was generally consistent with the Basel NSFR, but has some characteristics of U.S. market 3. Proposed rule: maintaining ratio of ASF equal or greater than the minimum funding needs (RSF) over a 1 year horizon to be minimum 1.0. The Final Rule
İngilizce ile karşılaştır
• The final rule assigns a zero percent RSF factor to unencumbered level 1 liquid assetİngilizce ile karşılaştır
securities and certain short-term secured lending transactions backed by level 1 liquid asset securities
İngilizce ile karşılaştır
• The final rule provides more favorable treatment for certain affiliate sweep deposits andİngilizce ile karşılaştır
non-deposit retail funding
İngilizce ile karşılaştır
• The final rule permits cash variation margin to be eligible to offset a covered company'sİngilizce ile karşılaştır
current exposures under its derivatives transactions even if it does not meet all of the criteria in the agencies' supplementary leverage ratio rule (SLR rule). In addition, variation margin received in the form of rehypothecatable level 1 liquid asset securities also would be eligible to offset a covered company's current exposures
İngilizce ile karşılaştır
• The final rule reduces the amount of a covered company's gross derivatives liabilitiesİngilizce ile karşılaştır
that will be assigned a 100 percent RSF factor Application of the final rule. The agencies have decided to break down the application/companies into 4 categories:
İngilizce ile karşılaştır
• Category I: US global systemically important banks (GSIBs) and any of their depositoryİngilizce ile karşılaştır
institution subsidiaries with >=$10Bn in consolidated assets
İngilizce ile karşılaştır
• Category II: Top-tier banking organizations, other than US GSIBs, with >=$700Bn inİngilizce ile karşılaştır
consolidated assets of >=$75Bn in average cross-jurisdiction activity, and to their depository institutions with >=$10Bn in consolidated assets.
İngilizce ile karşılaştır
• Category III: Top-tier banking organizations that have >=$250Bn in consolidatedİngilizce ile karşılaştır
assets, or that have >$100Bn in consolidated assets and also have >=$75Bn or more in:
İngilizce ile karşılaştır
o Average nonbank assetsİngilizce ile karşılaştır
o Average weighted short-term wholesale fundingİngilizce ile karşılaştır
o Average off-balance sheet exposure (not in Category I or II)İngilizce ile karşılaştır
• Category IV: Top-tier depository institutions holding companies or US intermediateİngilizce ile karşılaştır
holding companies that in each case have >=$100Bn in consolidated assets and >=$50Bn average weighted short-term wholesale funding (not in Category I, II, or III) NFSR Requirements by Category 1. Category I: 100% 2. Category II: 100% 3. Category III: 85% 4. Category IV: 70% Short Sales - I SUGGEST YOU READ THE WHOLE SECTION (IT IS GOLD) (https://www.federalregister.gov/d/2020-26546/p-810)