英語と比較
英語と比較
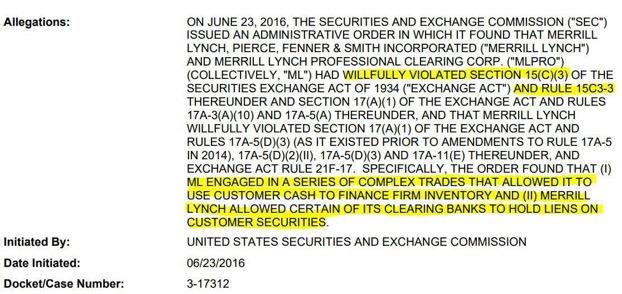
Prerequisite DD: 1. Citadel Has No Clothes 2. The EVERYTHING Short 3. The House of Cards – Part 1 4. The House of Cards - Part 2 ____________________________________________________________________________________________________________ TL;DR- No freaking way I can do that. _____________________________________________________________________________________________________________________ Continuing from HOC Part II... 4. Slimy… If you watched the AMA with Wes Christian, he talks about the number of occurrences where the actual short interest is severely understated based on the data his firm obtained for legal proceedings. According to his numbers, in most cases the short interest is 50% - 150% MORE than what is reported by the SEC (starting at 14:30). The objective isn’t to address the issue: it’s to keep the issue hidden. Firms that underreport their short interest are gaming the system by taking advantage of how the short interest calculation is done. When the SEC relies on reports that broker-dealers provide, and FINRA takes YEARS to reveal the lies within those reports, the broker-dealer can lie without immediately facing the consequences. It allows these firms to operate in a high-risk environment without exposing just HOW big their risk-appetite is. Another example that Wes mentioned was Merrill Lynch. Merrill was fined $415,000,000 (violation 3) in 2016 for using securities held in their customer’s accounts to cover their own trades. Check out this screenshot I took from that case:
英語と比較
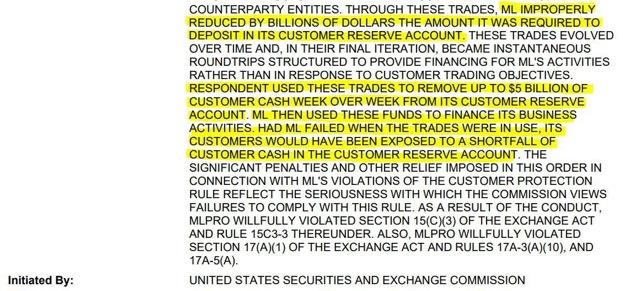
Remember when we mentioned SEA 15c3-3 in the case with Apex? They were asking customers to book short positions to either a cash account or a short margin account. SEA 15c3-3 protects those customers from allowing brokers to lend out the securities within their cash accounts… Well Merrill Lynch knocked that one right out of the f*cking park…
英語と比較
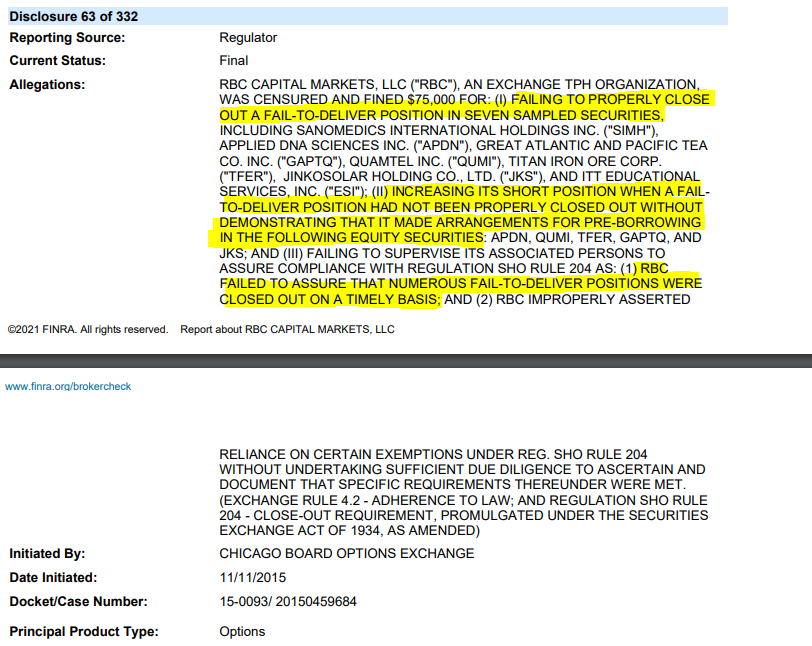
Merrill made it seem like the required deposit in their customer reserve account was much lower than it truly was. They wouldn’t have been able to use that cash if it reduced the amount below the minimum capital requirement, so they found a way to fudge the numbers. In doing so, they managed to prevent a CODE RED while reaping the benefits of a high-risk ‘opportunity’. Should Merrill have filed bankruptcy during that time, those customers would have been completely blindsided. In the case of short selling, the true exposure of short interest is unknown… and I’m not just talking about the short sale indicator. When a firm fails to deliver securities that were sold short, there’s a pretty good indication that they’ve exposed themselves to a bit of a problem.. Now imagine a case where the FTDs start piling up and they STILL continue to short sell that same security.. think I’m joking? Check out the Royal Bank of Canada:
英語と比較
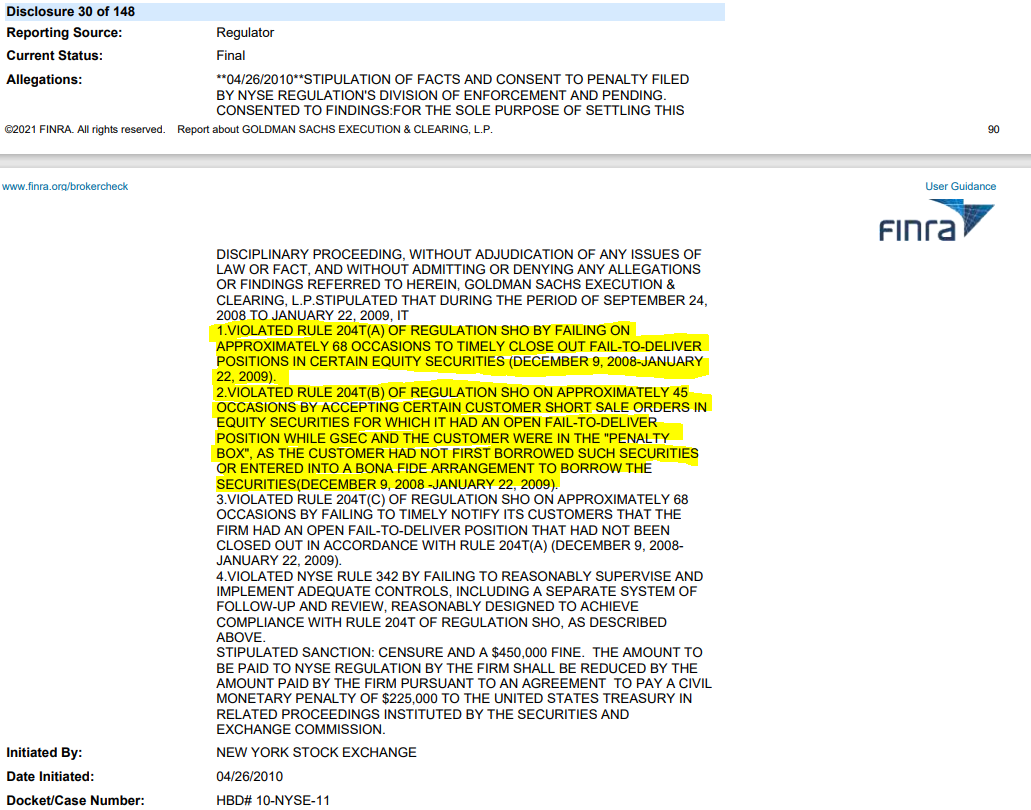
Again… I was pretty shocked at that one. However, nothing rang-the-bell quite like this one from Goldman Sachs:
英語と比較
Goldman had 68 occasions in 4 months where they didn’t close a failure-to-deliver… In 45 occasions, they CONTINUED to accept customer short sale orders in securities which it had an active failure-to- deliver… When a firm is really starting to sweat, they pull certain tricks out of their ass to quell the situation. Again, this is nothing but smoke and mirrors because that’s all they can really do. Just as Merrill Lynch artificially lowered their customer reserve deposit, other firms make it look like they cover their short positions. One of the ways they do this is by short selling a SH*T load of shares right before a buy-in… Since we’re talking about Goldman Sachs, this seems like a great time to showcase their experience with this..
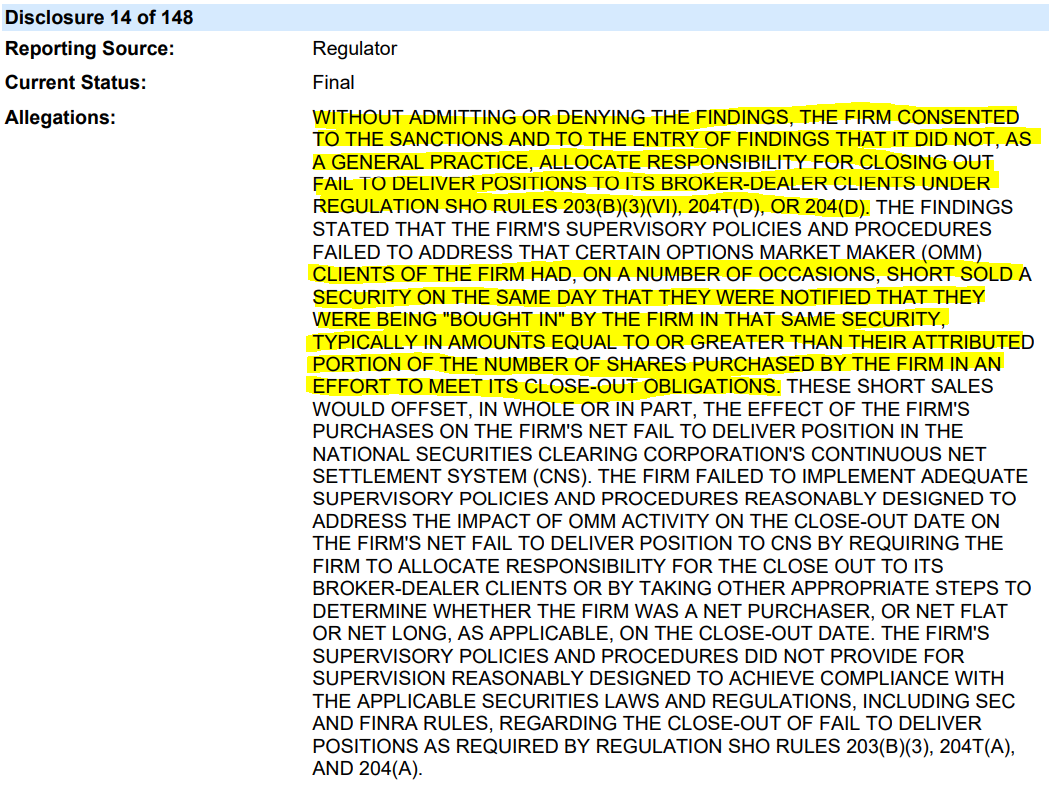
英語と比較
I promise… It really is as dumb as it sounds… So the perception here is when Goldman’s client has a FTD and they find out a buy-in is coming, the required buy-in would obviously be too extreme for the client to handle.. So they begin to buy those shares while simultaneously shorting AT LEAST the same amount they were required to purchase… Have you ever failed to repay a loan so you went to another bank and got a loan to cover the first one? Well that’s exactly what this is… I know what you’re probably thinking… “didn’t that just kick the can down the road?”. The answer is YES: it didn’t actually solve anything.. There’s still one more citation that Goldman received which truly represents the pinnacle of no-sh*ts- given. After I cover this, I don’t know how anyone could argue the systematic risks that exist within the securities lending business.. Check it out:
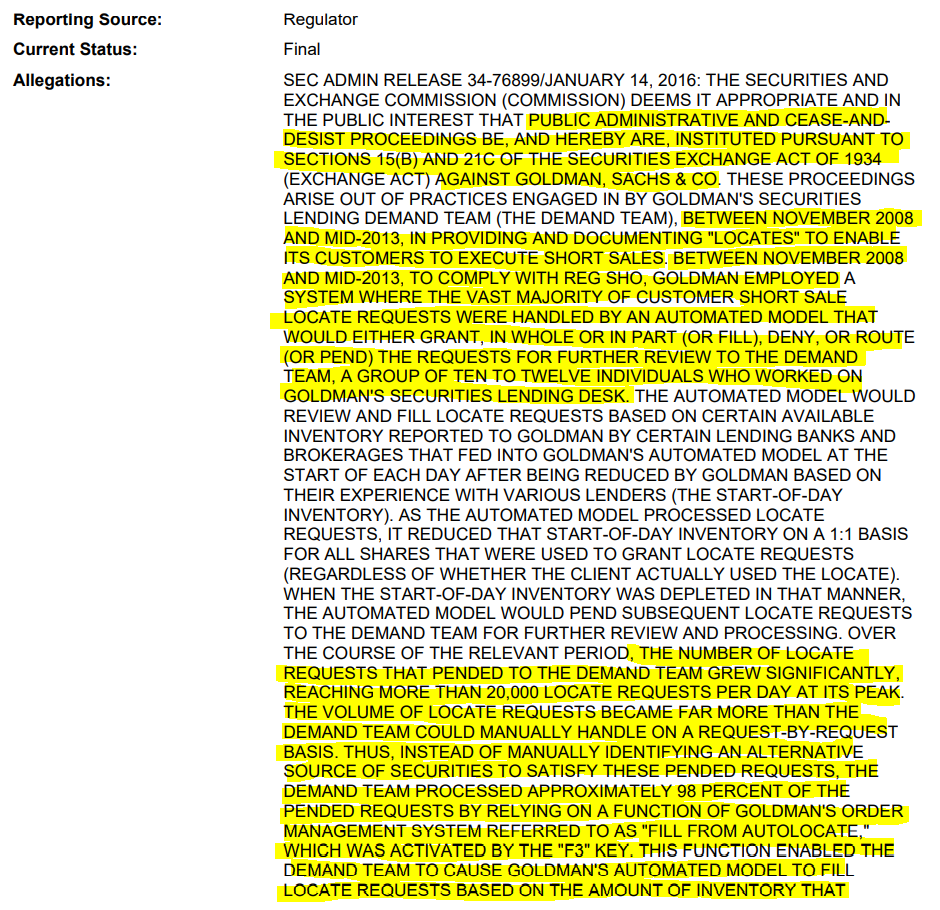
英語と比較
For 5 years, Goldman relied on a team of 10-12 individuals to locate shares to be used by its clients for short selling. This group was known as the “demand team”. Naturally, as the number of requests coming in the door started to increase, it became difficult for the team to properly document all of them. The volume peaked at 20,000 requests PER DAY, but the number of individuals that handled this job stayed the same. Obviously, this became too much for them to handle so they opted out of the manual process and found another solution- the F3 key…. Yes- the F3 key… This button activated an autofill system which completed 98% of Goldman’s orders to locate shares
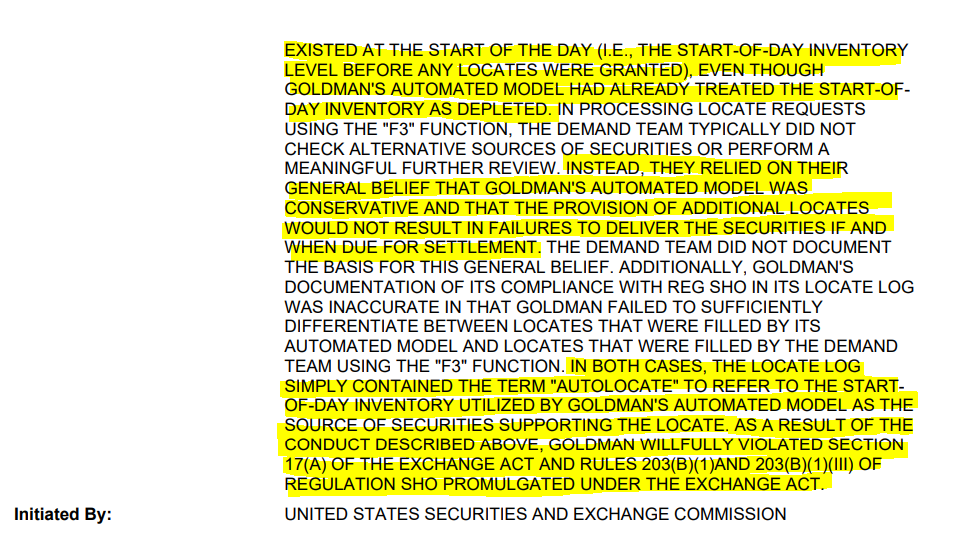
英語と比較
The problem with Goldman’s autofill system was that it used the number of shares available to borrow at the beginning of that day, which had already been accounted for. After using the auto-locate feature, the demand team didn’t even verify the accuracy of the autofill feature or document which method was used to locate the shares for each order… and this happened for 5 years.. Just goes to show how dedicated firms like Goldman Sachs truly are to the smallest of details, you know? Great f*cking work, guys. By the way, I have to show one of Goldman’s short sale indicator violations… It’s too good to pass up.
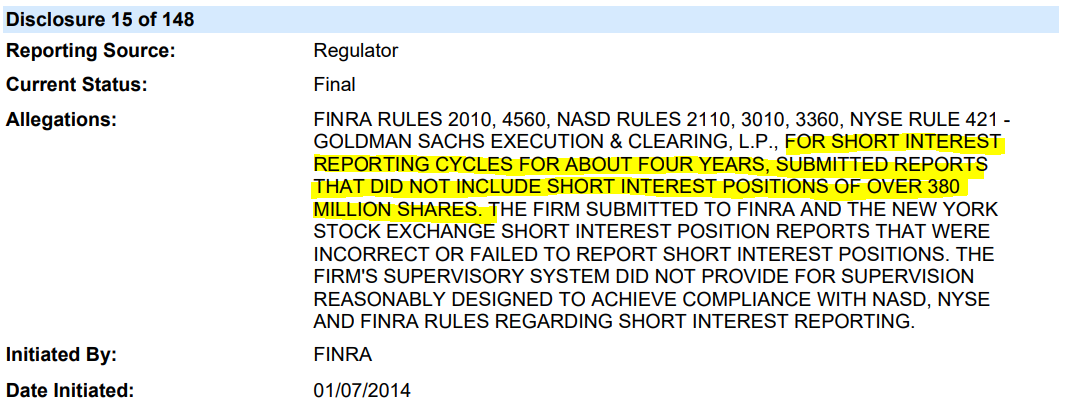
英語と比較
At some point, you just have to laugh at these ass clowns… I mean seriously… one violation for a 4 year period involving over 380,000,000 short interest positions… they have plenty of other short interest violations, I just laughed at how the magnitude of this one was summarized by FINRA with 10 lines and roughly 4 minutes... whoever wrote that one must have been late for lunch.. The last thing I’d like to note here is the way in which short sellers use options to “cover” their positions. Wes gave a great overview of this in the AMA (starting at 6:25). Basically, one group will buy puts and another group buys calls. This creates a synthetic share that is only provided if the option is activated. Regardless, short sellers will use that synthetic share to cover their short position and the regulators actually accept it… However, as Wes points out, most of those options expire without being activated which means the share is never delivered. This expiration can be set months down the road and allows the short seller to keep kicking the can. I doubt I need to say this, but we all remember the wild options activity that was happening shortly after GameStop spiked in January. u/HeyItsPixel was one of the first to point this out. While a lot of that activity was on the retail front, I suspect a lot of it was done by short sellers to cover those positions. ____________________________________________________________________________________________________________ 5. Hedgies are f*cked… I’m officially +20 pages deep and there’s still so much I’d like to say. It’s best saved for another time and
英語と比較
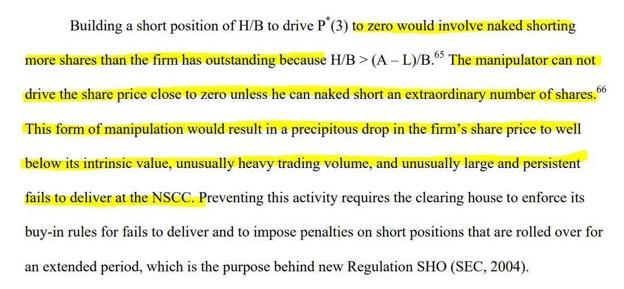
another post, I suppose. So I guess I’ll wrap all of this up with some of the best news I can possibly provide… It all started with a 73 page PDF that was published in 2005 by a silverback named John D. Finnerty. John was a Professor of Finance at Fordham University when he published “short selling, death spiral convertibles, and the profitability of stock manipulation”. The document is loaded with sh*t that’s incredibly relevant today, especially when it comes to naked short selling. He dives into the exact formula that short sellers use, which is far beyond what my wrinkled brain can interpret, alone… ..However, when firms are naked shorting a company with the goal of bankrupting them, they leave footprints which are only explained by this event. The proof is in the pudding, so to speak..
英語と比較
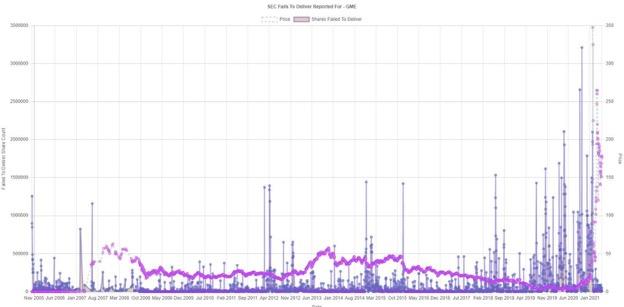
Any of this sound familiar?? “The manipulator can not drive the share price close to zero unless he can naked short an extraordinary number of shares… this form of manipulation would result in… unusually heavy trading volume, and unusually large and persistent fails to deliver at the NSCC”. Anyone else remember the volume in GME during the run-up in January? The total volume traded between 1/31/2021 and 2/5/2021 was 1,508,793,439 shares, or an average daily trade volume of 88,752,555 shares. On 1/22/2021, the volume reached 197,157,946… that’s roughly 3x the number of shares that exist.. if this doesn’t sound like unusual volume then I’m not sure what is. Furthermore, the FTD report on GameStop was through the roof during this time:
英語と比較
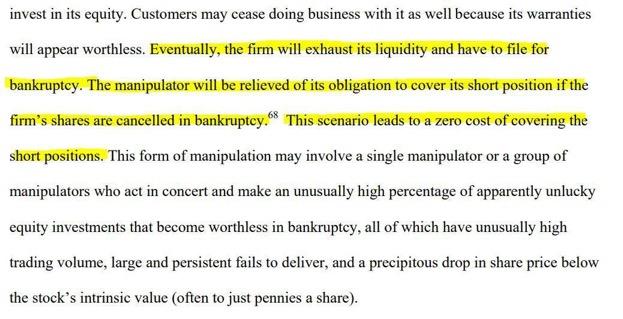
Notice the statement where the manipulator will be relieved of its obligation to cover IF the firm’s shares are cancelled in bankruptcy? Did you happen to see footnotes 65 & 66 in the first screenshot of his PDF? It references a company that he used for his analysis…

英語と比較
Charter Communications had a whopping 241.8% short float in 2005… The ONLY way the manipulator could have escaped this was by bankrupting the company and relieving the obligation to repurchase those shares… Guess what happened to Charter? They filed for bankruptcy in 2009… However, unlike John’s example where naked short sellers were driving down the price without opposition, GameStop had extremely high demand from retail investors to counter this activity. As I have discussed with Dr. T and Carl Hagberg, the run-up in volume during January and February was largely conducted by naked short sellers in an attempt to suppress the share price. As I have shown in the example with Goldman Sachs, firms will short sell during a buy-in for the same exact reason. To stabilize the price, you must stabilize supply and demand. …You know what Charter didn’t have? AN ARMY OF APES TO HODL THE STONK
英語と比較
DIAMOND. F*CKING. HANDS